



Key Highlights
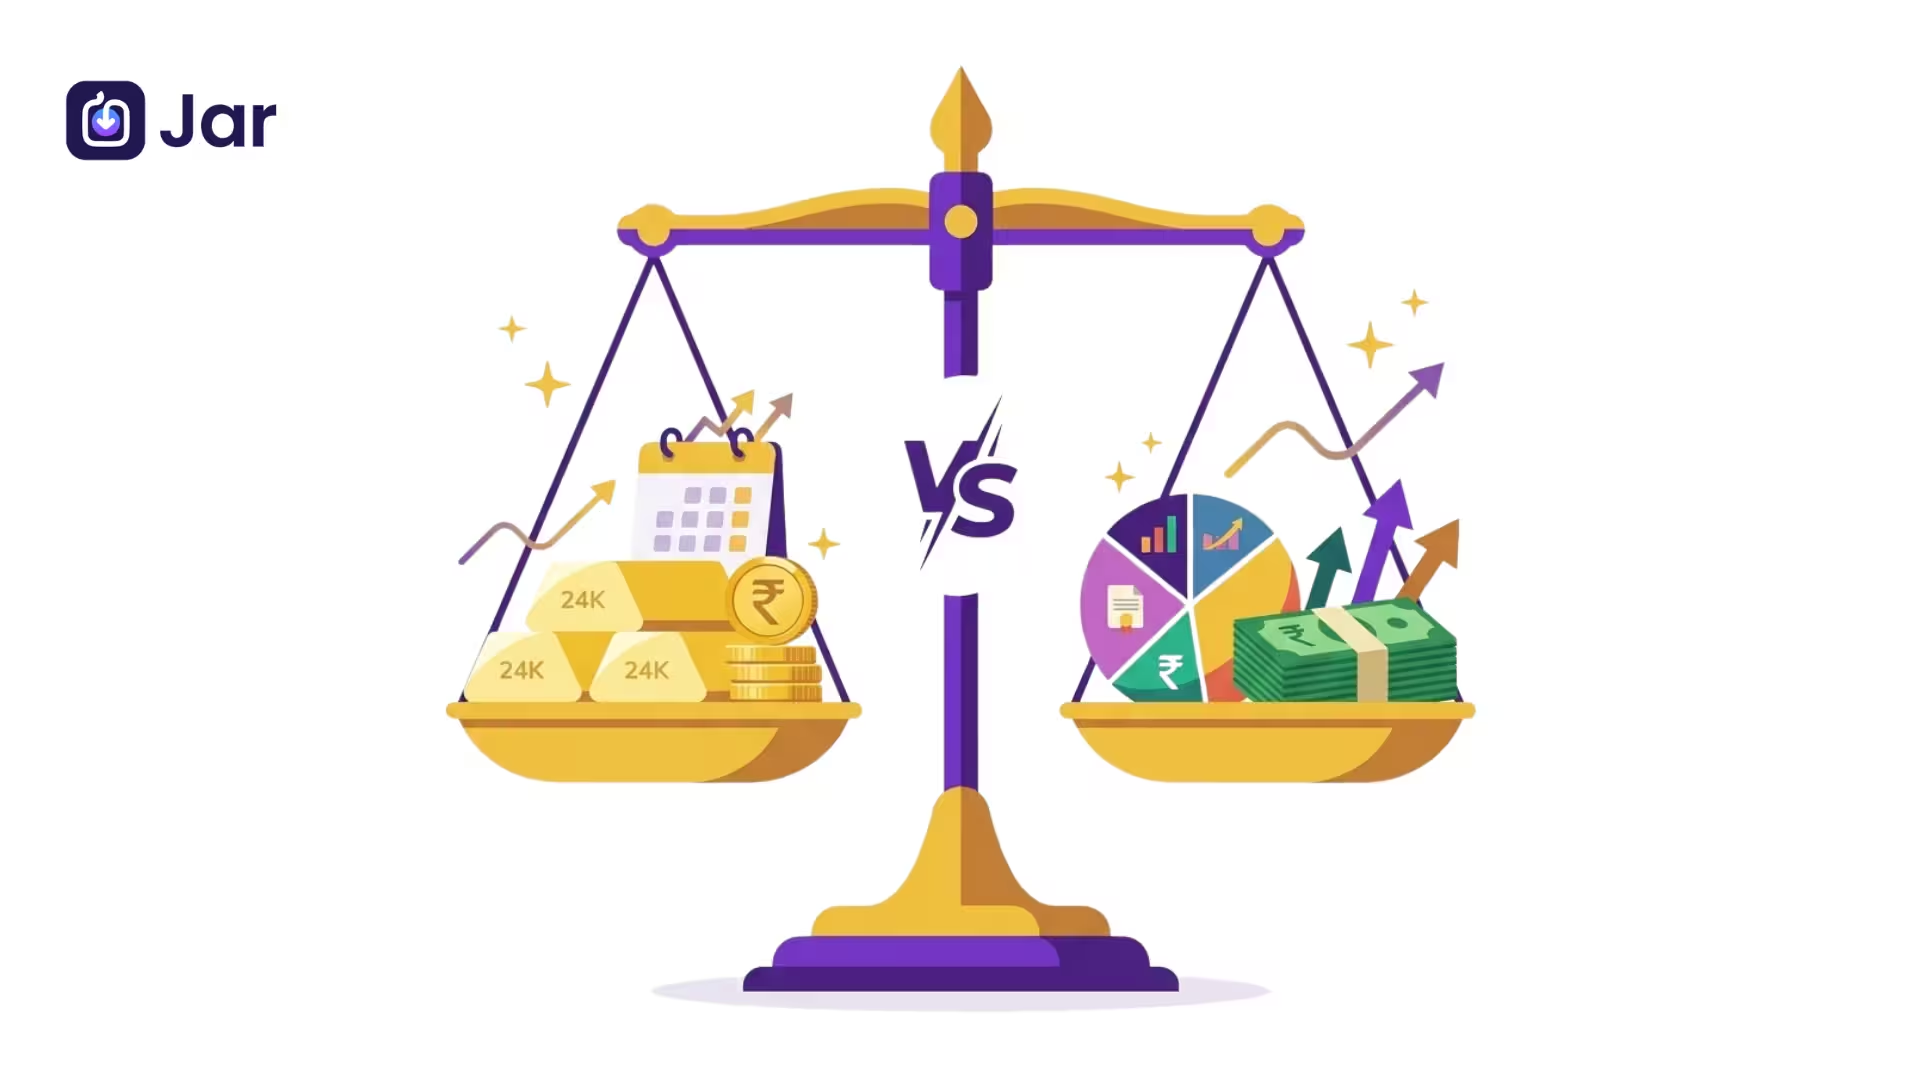
- Gold SIP vs mutual fund is really a question of which asset should play which role in your portfolio: gold protects, mutual funds grow.
- A gold SIP can take the form of digital gold, a gold mutual fund, or regular purchases of physical gold.
- Mutual fund SIPs invest in stocks, bonds or both, and suit long-term wealth building.
- Gold is generally less volatile, while mutual funds move more with market conditions.
- Equity mutual funds have higher long-term growth potential, though returns vary widely.
- Gold is usually easy to sell, while mutual fund redemptions follow a settlement cycle.
- Costs differ: physical gold carries making charges and storage, while funds carry expense ratios and possible exit loads.
- Tax rules apply to both and have changed over time, so always check the latest rules.
- Gold ETFs and gold mutual funds are two different ways to hold the same metal.
- Many investors combine a core mutual fund SIP with a smaller gold allocation.
- Chasing past returns and stopping SIPs during a downturn are two common mistakes.
- The FAQ section answers questions on minimum amounts, inflation and which option suits beginners.
Monthly SIPs have quietly become a habit for many Indian investors, and gold is now part of that conversation too. So when you weigh gold SIP vs mutual fund, the real question is where your regular money should work hardest: in a metal that holds its value, or in a portfolio that grows with markets.
Indian households hold roughly $3.8 trillion worth of gold, which shows how deeply the metal is tied to family savings. Yet the two options behave very differently when markets fall, when you need cash in a hurry, and when you are aiming for growth over ten years.
In this guide, you will learn how gold and mutual fund SIPs compare on risk, returns, liquidity, costs and tax, who each one suits, and how a blended plan can work for you.
Quick Snapshot
| Factor | Gold SIP | Mutual Fund SIP |
| What you own | Gold, held digitally, as fund units, or physically | Units in a pool of stocks, bonds or both |
| Risk level | Generally lower and steadier | Moderate to high, depending on fund type |
| Return potential | Typically moderate, roughly high single digits to about 10% over long periods | Higher potential over long periods, but varies widely |
| Volatility | Lower | Higher, as prices follow markets |
| Liquidity | High; digital gold sells on the platform, and gold ETFs trade on exchanges | Open-ended funds redeem at NAV and settle over a few working days |
| Costs | Making charges and storage for physical gold; platform or fund charges for digital gold | Expense ratio and, in some cases, exit load |
| Diversification | Low, since it is a single asset | High, across companies, sectors or asset classes |
| Inflation protection | Commonly seen as a hedge | Depends on whether returns beat inflation over time |
| Best suited for | Stability, a hedge, a smaller allocation | Long-term wealth creation and goal-based investing |
Gold SIP vs Mutual Fund: The Basics Before You Choose
What a gold SIP really means
A gold SIP is a recurring purchase of gold instead of a single lump-sum buy. It can take a few forms. A digital gold SIP lets you pick an amount and a frequency, and the metal is held in insured vaults with a digital record of your holding.
A gold mutual fund SIP invests in gold-linked securities, usually gold ETFs, so you never touch the metal yourself. Some people also buy coins or bars in regular instalments, though that route brings storage concerns and making charges.
Start building your wealth with 24K pure digital gold today—download the Jar app and set up your automated Gold SIP with as little as ₹10!
How mutual fund SIPs work
A mutual fund pools money from many investors and puts it into stocks, bonds or both, depending on the scheme's objective. Each monthly SIP instalment buys units at the prevailing NAV.
Over time, you buy more units when prices are low and fewer when prices are high, which is one reason SIPs suit disciplined investors who do not want to time the market. Schemes come in many types, including large-cap, mid-cap, small-cap, multi-cap, debt and hybrid funds, and each carries a different risk level.
Long-Term Returns: What the Numbers Suggest
Gold's long-term return is often placed in the high single digits to around 10% a year, though the exact figure depends on the period you measure. Its strength lies less in fast growth and more in preserving value over years. Gold does not pay interest or dividends, so your returns come only from changes in its price.
Mutual fund returns
Equity mutual funds have the higher growth potential. Over long horizons, they have generally outpaced gold, but the gap depends heavily on the category and the time window. Some years are negative, and small-cap funds swing more than large-cap ones.
Debt funds sit closer to gold's return range and can suit goals where you want steadier, lower-risk growth. Whatever the category, compounding works best when you stay invested through ups and downs, and past performance never guarantees the future.
Risk and Volatility: Which One Lets You Sleep Better?
Gold is usually the calmer of the two. Its price can still move with global events, currency shifts and interest rate expectations, but it tends to hold steady when equity markets are under stress. That is why many investors treat it as a cushion.
Mutual funds are market-linked, so their value rises and falls with the securities they hold. Equity funds carry moderate to high risk, and the risk rises as you move from large-cap to mid-cap and small-cap schemes.
Professional fund managers make the buying and selling decisions for you, which helps some investors, but it does not remove market risk. If a sharp fall would make you panic and redeem, a high-equity SIP may not match your temperament.
Liquidity: How Fast Can You Turn It Into Cash?
Gold is one of the easier assets to convert into cash. Digital gold can be sold on the platform at the live rate, and physical gold can be sold to a jeweller or dealer. Keep in mind that a dealer may offer a price below the headline rate after margins, and jewellery may fetch less than its weight-based value.
Mutual funds work differently. Open-ended funds redeem at the day's NAV, and the money usually reaches your account after a few working days.
Exchange-traded funds can be bought and sold during market hours, but you need a demat and trading account for that. So liquidity for a mutual fund depends on the fund type, and it is worth checking the redemption timeline before you invest.
Costs and Charges
Physical gold carries making charges on jewellery, GST and, if you store it at home or in a locker, storage and insurance costs. Digital gold generally has lower charges, though platforms may levy their own fees, and you should check the buying and selling spread.
Mutual funds charge an expense ratio, which covers fund management and operating costs. Some schemes also apply an exit load if you redeem within a set period. Gold ETFs usually avoid exit loads but bring brokerage and demat charges.
Expense ratios differ from scheme to scheme, so compare the figures in the fund's documents rather than assuming they are the same.
Tax Treatment: Check the Rules Before You Invest
Gains from both gold and mutual funds are taxed as capital gains when you sell at a profit. How much you pay depends on the asset type and how long you hold it, and the rules have been revised in recent budgets. Equity-linked savings schemes (ELSS) offer a deduction on the invested amount under the old tax regime, which makes them a popular choice for tax planning. Sovereign Gold Bonds can also offer tax advantages in specific situations, so check the terms of the tranche you are considering.
Because thresholds and rates change, confirm the latest figures with a tax professional or the official income tax portal before you plan your sales or file your returns.
Diversification and Inflation: Why Both Matter
Diversification means not putting all your eggs in one basket. A mutual fund spreads money across many companies or asset classes, which lowers the impact of any single business doing badly. Gold is a single asset, so it adds diversification of a different kind: it often behaves differently from equities.
On inflation, gold is widely seen as a hedge. When the cost of living rises, gold prices often rise too, so it can help protect purchasing power. Equity mutual funds aim to beat inflation over long periods, but they do not guarantee it in any given year. In short, gold protects value, and mutual funds help your money grow faster than prices rise.
Who Should Choose a Gold SIP?
A gold SIP may suit you if you:
- Prefer steadier value and want something that tends to hold up during market stress.
- Want a hedge against inflation or global uncertainty.
- Are comfortable with a lower return potential in exchange for lower volatility.
- Want a smaller, supporting position in your overall portfolio rather than the main engine.
- Prefer buying a precious metal in small, regular amounts without storing it yourself.
Who Should Choose a Mutual Fund SIP?
A mutual fund SIP may suit you if you:
- Are investing for goals five to ten years or more away.
- Want your money to grow through compounding and market participation.
- Can handle short-term ups and downs without redeeming in a panic.
- Prefer professional management and a wide spread of holdings.
- Want flexibility across different risk levels, from debt funds to equity funds.
Gold ETF vs Gold Mutual Fund: Two Ways to Hold Gold
If you want gold exposure through a fund, you will often meet two options. A gold ETF tracks the price of gold and represents a unit linked to roughly one gram of 99.5% pure gold. It trades on the stock exchange, so you need a demat and trading account, and you can buy or sell during market hours. It usually has no exit load, but brokerage and demat charges apply.
A gold mutual fund invests mainly in gold ETFs and other gold-related assets. You can invest without a demat account, and it can be set up as a SIP, which makes it convenient for regular investing.
Its units are redeemed at the end-of-day NAV, and exit loads may apply depending on the scheme. Some gold funds also allow small monthly SIP amounts, though minimums differ by scheme.
In short, pick a gold ETF if you want intraday flexibility and already have a demat account. Pick a gold mutual fund if you want a simple, SIP-friendly route without managing a demat account.
Can You Combine Both? A Blended Approach
Many investors do not have to choose one. A common approach is to keep the core of the portfolio in mutual funds for growth and add a smaller gold holding for stability. This keeps the growth engine running while cushioning the portfolio when markets fall.
The right mix depends on your age, income stability, goals and how you react to losses. Someone with a long horizon and steady income may lean more towards equity funds. Someone nearing a major goal may
want a bigger share in gold and debt.
Review the mix once a year, especially after large market moves, and rebalance if one side has drifted far from your plan.
Common Mistakes to Avoid
The first mistake is chasing last year's best-performing fund or the metal that has just rallied. Past returns rarely repeat on schedule. The second is stopping your SIP during a market fall, which is often when your instalments buy the most units.
The third is ignoring costs, since a small difference in expense ratio or making charges adds up over years. The fourth is buying physical gold only as an investment and forgetting about storage, insurance and resale margins.
Finally, many people start investing without an emergency fund, which can force them to redeem at the wrong time.
Conclusion
The gold SIP vs mutual fund decision comes down to your goals, time horizon and comfort with risk. Gold offers stability, liquidity and a hedge against inflation, though its return potential is more modest.
Mutual funds offer higher long-term growth potential, along with more market-linked ups and downs. For most investors, the sensible path is to decide which role each asset plays in the portfolio, check costs and tax rules, and keep investing steadily through market cycles.
Frequently Asked Questions
Which is a better investment: gold SIP or mutual fund SIP?
Neither is better for everyone. Mutual fund SIPs suit long-term wealth creation, while gold SIPs suit stability, inflation protection and diversification. Many investors use both, with mutual funds as the core and gold as a supporting holding.
Can I start a gold SIP with a small amount?
Digital gold platforms and some gold mutual funds allow small monthly amounts. Minimum amounts differ by platform and scheme, so check the terms before you start.
Is gold a good hedge against inflation?
Gold is widely considered a hedge against inflation, and it often holds value when prices rise. It does not always move in step with inflation in the short term, so it works best as a long-term component.
Are mutual funds safe for long-term investing?
Mutual funds carry market risk, so their value can fall in the short term. Over long periods and with a diversified approach, equity funds have historically offered growth potential, but no outcome is guaranteed.
Should a beginner choose gold or mutual funds first?
Most beginners start with a mutual fund SIP for long-term goals and add gold later as a smaller allocation. Build an emergency fund first so you are not forced to sell at a bad time.