



- Gold has been called “insurance for your money.” It holds value when inflation rises. It doesn’t move with stock markets. For these reasons, many Indians see gold as part of a balanced portfolio.
But there’s a problem: buying gold used to mean one thing—either jewelry or physical bars. Now there are many ways to invest in gold, each with different costs, convenience levels, and commitment requirements. And you don’t need thousands of rupees to start.
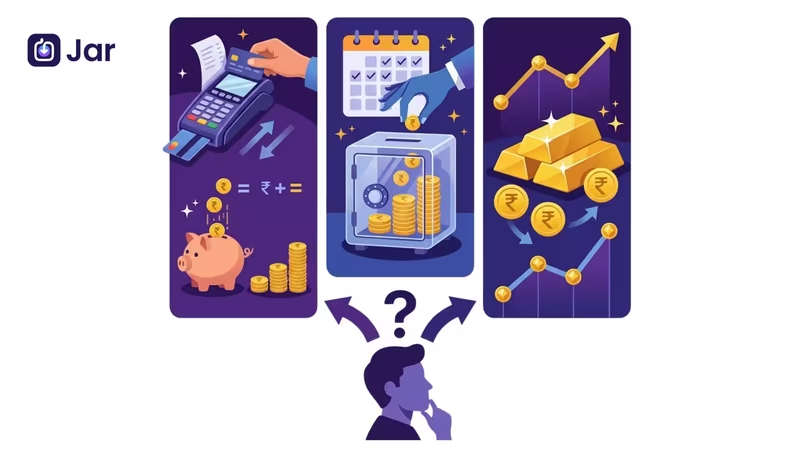
This article explains three practical paths to building gold holdings, starting from as little as ₹3 per transaction. Whether you’re a beginner with ₹30 a day or someone ready to commit ₹2,000 monthly, there’s a gold investment path that fits you.
Key Highlights
- Gold round-ups let you invest spare change from everyday spending into digital gold—the easiest entry point if you’ve never invested before.
- Daily gold savings turn a fixed daily amount directly into gold, building consistent holdings without requiring discipline for SIP dates.
- Gold SIPs (Systematic Investment Plans) automate monthly or weekly gold investments, using rupee-cost averaging to reduce the risk of buying at price peaks.
- Digital gold attracts 3% GST at purchase, while gold ETFs and mutual funds don’t—but compare all-in costs, including spreads, fees, and taxes.
- You can use all three methods together: round-ups for momentum, daily savings for consistency, and SIPs for structured long-term allocation.
Why Invest in Gold?
Before diving into methods, let’s answer why gold matters.
Gold has historically held its value when the rupee weakens. It doesn’t correlate tightly with stock markets, which means it balances a portfolio. It’s also tangible—you own it, unlike a stock certificate or mutual fund units sitting in a demat account.
However, gold prices fluctuate daily. Gold doesn’t generate dividends or interest. Returns depend entirely on price movement. So gold is best viewed as a portfolio stabilizer and inflation hedge, not a primary wealth-building tool.
With that context, let’s explore how to invest in gold with whatever you can spare.
Method 1: Gold Round-Ups—Investing Without Thinking
Round-ups are the easiest entry point to gold investing. They work exactly like savings round-ups, except the money goes directly into digital gold instead of sitting in cash.
How it works: Link your UPI or card to a digital gold app. Every transaction rounds up to the nearest figure, and the difference buys digital gold. For example, you spend ₹37 on groceries. The app rounds to ₹40 and buys ₹3 worth of digital gold.
What you own: Digital gold is gold stored in vaults, held on your behalf by the platform. You don’t physically hold it—the app tracks your grams of gold and its current value based on market prices.
Monthly accumulation: If you spend ₹10,000–₹15,000 monthly, round-ups might accumulate ₹200–₹400 worth of gold each month. It’s small but consistent.
Who it fits:
- First-time gold investors who want to start without commitment.
- People who struggle with fixed savings but spend regularly.
- Anyone curious about gold who wants to test it with minimal risk.
The real strength: It’s effortless. You’re already spending money. You’re just converting a portion of your spending into gold instead of letting it stay as cash.
The real limitation: Amounts are unpredictable. You can’t control how much gold accumulates. Also, you’re paying 3% GST on each purchase, which adds up. And you’re investing in digital gold specifically, which comes with regulatory gaps that we’ll discuss later.
Method 2: Daily Gold Savings—Consistent Gold Accumulation
Daily gold savings means committing a fixed daily amount to buying digital gold. Unlike round-ups, you control the amount and frequency.
How it works: You decide on a daily investment amount—say ₹50 per day. Either you manually buy ₹50 of digital gold each day, or the app auto-invests on your behalf. After 30 days, you’ve invested ₹1,500 and own approximately 2–3 grams of gold (depending on price).
What you own: Again, digital gold. Your holdings appear in the app as grams of gold, updated daily with current market value.
Monthly accumulation: If you invest ₹30–₹100 daily, you accumulate ₹900–₹3,000 worth of gold monthly. That’s roughly 1.3–4 grams depending on gold prices.
Who it fits:
- Salaried professionals with stable monthly income.
- Investors who want a predictable monthly gold addition.
- Anyone saving for a gold-backed goal (wedding, education fund) with a timeline.
The real strength: Predictability and discipline. You know exactly how much gold you’ll accumulate each month. The act of daily investing—even if it’s automated—builds confidence in gold ownership.
The real limitation: Again, you’re paying 3% GST on every purchase. With daily purchases, that GST compounds. You’re also locked into digital gold’s regulatory environment, which lacks the investor protection of regulated assets.
Method 3: Gold SIP—Structured Long-Term Allocation
A gold SIP is the “investor’s choice.” Instead of buying daily, you commit to investing a fixed amount at regular intervals—weekly or monthly—and you can choose how you invest: digital gold, gold ETF, or gold mutual fund.
How it works: You set up automatic monthly investments—say ₹2,000 every 1st of the month. On that date, ₹2,000 is invested in gold. You continue for months or years. The key benefit: you’re buying at different prices over time, which reduces the risk of buying entirely at a price peak.
This is called rupee-cost averaging. If gold is ₹6,500/gram one month and ₹6,000/gram the next, your fixed ₹2,000 buys more grams the second month. Over years, this evens out price volatility.
What you own: This depends on your choice:
- Digital gold SIP: You own digital gold, same as above. But you commit to a schedule, reducing transaction frequency.
- Gold ETF SIP: You own units of a gold ETF, which is a regulated fund that tracks gold prices. Held in a demat account.
- Gold mutual fund SIP: You own units of a mutual fund that invests in gold or gold ETFs. Also regulated.
Monthly accumulation: With a ₹2,000 monthly SIP, you invest ₹24,000 yearly. That’s roughly 35–40 grams of gold yearly (depending on price).
Who it fits:
- Investors who see gold as a portfolio component, not a speculation.
- People saving for long-term goals (children’s education, retirement diversification).
- Anyone comfortable with digital assets or demat accounts.
The real strength: Systematic, disciplined, long-term accumulation. Rupee-cost averaging works. And if you choose a regulated option (ETF or mutual fund), you get investor protection that digital gold lacks.
The real limitation: Gold prices can fall, so your SIP investment could lose value in the short term. You need patience and a long-term horizon.
The Cost Breakdown: Which Gold Investment Route Is Cheapest?
This is critical. Different methods have wildly different costs.
| Gold Route | Purchase Cost | Other Fees | Annual Expense | Tax on Sale |
| Digital Gold (any method) | 3% GST on purchase | Buy-sell spread (0.5–1.5%); possible delivery charges if redeemed as physical | None | LTCG at 12.5% after 24 months (or slab rate before) |
| Gold ETF | No GST | Brokerage (₹20–₹50 per trade); transaction charges (0.1%) | 0.4–0.6% p.a. | LTCG at 12.5% after 12 months (or slab rate before) |
| Gold Mutual Fund | No GST | None (built into NAV) | 0.5–1% p.a. | LTCG at 12.5% after 24 months (or slab rate before) |
The reality: Digital gold looks cheap upfront (it’s convenient, easy to start). But the 3% GST is a real cost that compounds with every purchase. If you’re using round-ups or daily savings, you’re making frequent small purchases, each subject to 3% GST. Over a year, that’s significant.
Gold ETFs have a slightly higher entry barrier (you need a demat account and brokerage knowledge) but lower ongoing costs, especially for regular investing.
Gold mutual funds sit in the middle—no GST, moderate fees, no demat account needed.
For a gold SIP specifically: If you’re investing ₹1,000–₹2,000 monthly, a gold ETF SIP is usually cheapest over 3+ years due to lower GST burden.
Digital Gold: Convenience vs. Regulation
Before you choose digital gold (whether round-ups, daily savings, or SIP), you need to understand a key risk.
SEBI (Securities and Exchange Board of India) has explicitly stated that digital gold products are not regulated as securities. They operate outside SEBI’s framework. This means:
- SEBI doesn’t oversee how platforms store gold or manage your account.
- If the platform fails, you’re not covered by investor-protection funds.
- The custodian (the vault holding your gold) may not be independently audited.
- Costs and spreads can be opaque.
Digital gold is not automatically unsafe. But it lacks the regulatory framework that gold ETFs and mutual funds have.
Before choosing digital gold, verify:
- Is the custodian clearly named and independently audited?
- Is there a buy-sell spread? How much?
- What are delivery charges if you want physical gold?
- Can you access customer support easily?
- Is the company registered and traceable?
If you want stronger protection: Choose a gold ETF or gold mutual fund. These are regulated by SEBI. Costs are transparent. If the fund company fails, your units are safe.
Complete Comparison: All Three Methods Side-by-Side
| Aspect | Gold Round-Ups | Daily Gold Savings | Gold SIP |
| Entry Method | Link UPI/card; rounds up automatically | Set daily amount or auto-invest | Monthly/weekly auto-investment |
| Effort | Minimal (completely passive) | Low (set once, runs auto) | Low (set once, runs auto) |
| Investment Amount | ₹1–₹9 per transaction | ₹10–₹100 daily | ₹500–₹10,000 monthly |
| Monthly Gold Accumulation | ₹200–₹500 (unpredictable) | ₹900–₹3,000 (might vary on daily investment value) | ₹500–₹10,000 (fixed) |
| Gold Ownership Form | Digital gold only | Digital gold only | Digital gold, ETF, or mutual fund |
| Other Ongoing Costs | Buy-sell spread | Buy-sell spread | ETF: 0.4–0.6% p.a.; MF: 0.5–1% p.a. |
| Liquidity | High (sell anytime) | High (sell anytime) | High (sell anytime) |
| Regulation | Unregulated digital gold | Unregulated digital gold | Regulated (if ETF/MF) |
| Best For | First-time investors; testing | Regular savers with income | Long-term wealth building |
| Suitable Starting Age | 18+ with income | 18+ with income | 18+ with stable income |
| Can Be Combined with other Investments? | Yes | Yes | Yes |
How to Build a Gold Portfolio: A Staged Approach
Don’t commit to one method. Think of these as stages in a gold-building journey.
Stage 1: Test with Round-Ups (Months 1–3)
Start a gold round-ups app. Don’t overthink it. After three months, you’ll have ₹500–₹1,500 worth of digital gold. You’ll understand how gold prices move and feel confident owning gold.
Stage 2: Add Daily Gold Savings (Months 4+)
Once you’re comfortable, add ₹30–₹50 daily to digital gold. Now you’re building gold more intentionally while round-ups continue passively. After 6–12 months, you’ll have accumulated 5–10 grams.
Stage 3: Switch to a Structured Gold SIP (Month 12+)
Once you have consistent income and a clear timeline, move to a gold SIP. Choose a gold ETF if you want lower costs, or a gold mutual fund if you want simplicity. Commit to ₹1,000–₹2,000 monthly.
Why this progression works:
- Round-ups build confidence with zero friction.
- Daily savings develop your investing habit.
- A gold SIP turns that habit into long-term wealth building with lower costs.
A Practical Example
Let’s see how this works with real numbers.
Scenario: Arjun is 26, works as a data analyst, earns ₹50,000/month, and wants to own gold but doesn’t know where to start.
Month 1–3: Gold Round-Ups Only
Arjun links his UPI to a digital gold round-ups app. He doesn’t change his spending. After three months, round-ups accumulate ₹800 worth of gold (~1.2 grams). He’s surprised and intrigued.
Month 4–12: Round-Ups + Daily Gold Savings
Arjun decides to also invest ₹50 daily in digital gold. That’s ₹1,500/month. By month 12:
- Round-ups: ₹3,200 worth of gold (~5 grams, with price fluctuations)
- Daily savings: ₹18,000 invested in gold (~28 grams)
- Total: ~33 grams of digital gold, ₹21,200 invested
Month 13 onward: Transition to Gold SIP in ETF
Arjun opens a demat account and switches to a monthly gold ETF SIP of ₹2,000. He stops the daily digital gold savings (though he could keep it running). His round-ups continue.
By Month 24:
- Gold SIP over 12 months: ₹24,000 invested in a gold ETF (~36–40 grams, depending on prices)
- Round-ups: Additional ₹3,200 in digital gold
- Total gold: ~70–75 grams
Cost comparison:
- Digital gold route (round-ups + daily): ~₹640 in GST (3% on ₹21,200)
- Gold ETF SIP: ₹0 GST; ~₹120 in total fees (0.5% annually on ₹24,000)
Over time, the ETF SIP becomes much cheaper.
Key Takeaways
Gold investing has no one-size-fits-all path. Round-ups are perfect for starting. Daily gold savings builds discipline. A gold SIP creates long-term holdings with lower costs.
The progression makes sense: build confidence with round-ups, establish the habit with daily savings, then scale with a structured SIP.
And choose your gold route carefully. Digital gold is convenient but unregulated and costly due to GST. A gold ETF or mutual fund SIP offers regulation, transparency, and lower long-term costs.
Start small. Gold prices change daily, but over years, consistent buying through rupee-cost averaging smooths out volatility. That’s the real power of these approaches.
Start Round-off, Daily saving, Weekly saving or Monthly saving now in 24k Digital Gold with the Jar app.
Frequently Asked Questions
What’s the difference between digital gold and a gold ETF?
Digital gold is unregulated; you own gold stored in a vault managed by a private platform. A gold ETF is regulated by SEBI; you own shares of a fund that holds gold, and your shares trade on a stock exchange. Gold ETFs offer more transparency and protection.
Can I switch from digital gold to a gold ETF later?
Yes, but you’ll need to sell your digital gold first (paying any applicable charges), then invest the cash in a gold ETF. There’s no direct conversion. Plan this ahead to minimize taxes.
How much gold should I own?
Financial advisors often suggest 5–10% of your portfolio in gold. As an inflation hedge, not a wealth-building tool. The exact amount depends on your overall portfolio, risk tolerance, and goals.
Will gold prices keep rising?
No one can predict gold prices. Gold can rise, fall, or stay flat. Historical data shows gold holds value over long periods, but short-term volatility is real. That’s why a SIP—buying regularly regardless of price—works better than trying to time the market.
What if gold prices fall after I invest?
If you’re holding for the long term (5+ years), price dips usually recover. A gold SIP actually benefits from falling prices (your money buys more grams). If you need the gold in the next 2 years, gold might not be appropriate.
Are there limits on how much gold I can own?
There’s no legal limit on digital gold ownership. For physical gold, India has no limit on ownership quantity. However, physical gold above 20g for unmarried women or 100g for married women triggers reporting requirements. Digital gold and ETFs don’t have these restrictions.
Can I redeem digital gold as physical gold?
Yes, most digital gold apps let you convert to physical gold. But delivery charges apply, typically ₹50–₹500 depending on quantity. For small amounts, physical delivery isn’t cost-effective.
Does a gold savings app read your SMS? Permissions explained.
Apps ask for certain permissions to function—like access to your bank account, contact details, or SMS. These permissions can feel invasive, but they serve specific purposes.
If a gold or savings app asks for SMS access, it’s usually to verify transactions or read OTPs (one-time passwords) sent by your bank. This is a security feature that protects your account.
However, you should check:
- Does the app clearly explain why it needs each permission?
- Is the app from a registered company or known platform?
- Does the platform have transparent privacy and security policies?
- Can you grant permissions selectively (modern Android and iOS let you turn permissions on/off)?
Legitimate apps ask only for the permissions they actually need. If an app asks for access to everything—your photos, calendar, contacts, and SMS—without a clear reason, that’s a red flag. You don’t have to give an app every permission it requests. Grant only what’s necessary.
Before installing any financial app, read the privacy policy and reviews. If something feels off, use a different platform. There are many options.
What’s the tax on selling gold?
Long-term capital gains (holding 12+ months for ETFs, 24+ months for digital gold/mutual funds) are taxed at 12.5% without inflation indexation. Short-term gains are taxed at your income slab rate. Professional tax advice is helpful when selling.
Final Note
Gold is simple when you stop overthinking it. It holds value. It diversifies a portfolio. And modern methods—round-ups, daily savings, SIPs—let you build gold holdings in small, manageable increments.
The method you choose depends on where you are today. Start where it’s easiest (round-ups), graduate to what’s disciplined (daily savings), then move to what’s structured (SIPs).
Build your gold gradually, consistently, and without pressure. Time and rupee-cost averaging will do the rest.